# Mastercard Launches Smart MCC Routing to Reduce Gambling Transaction Declines
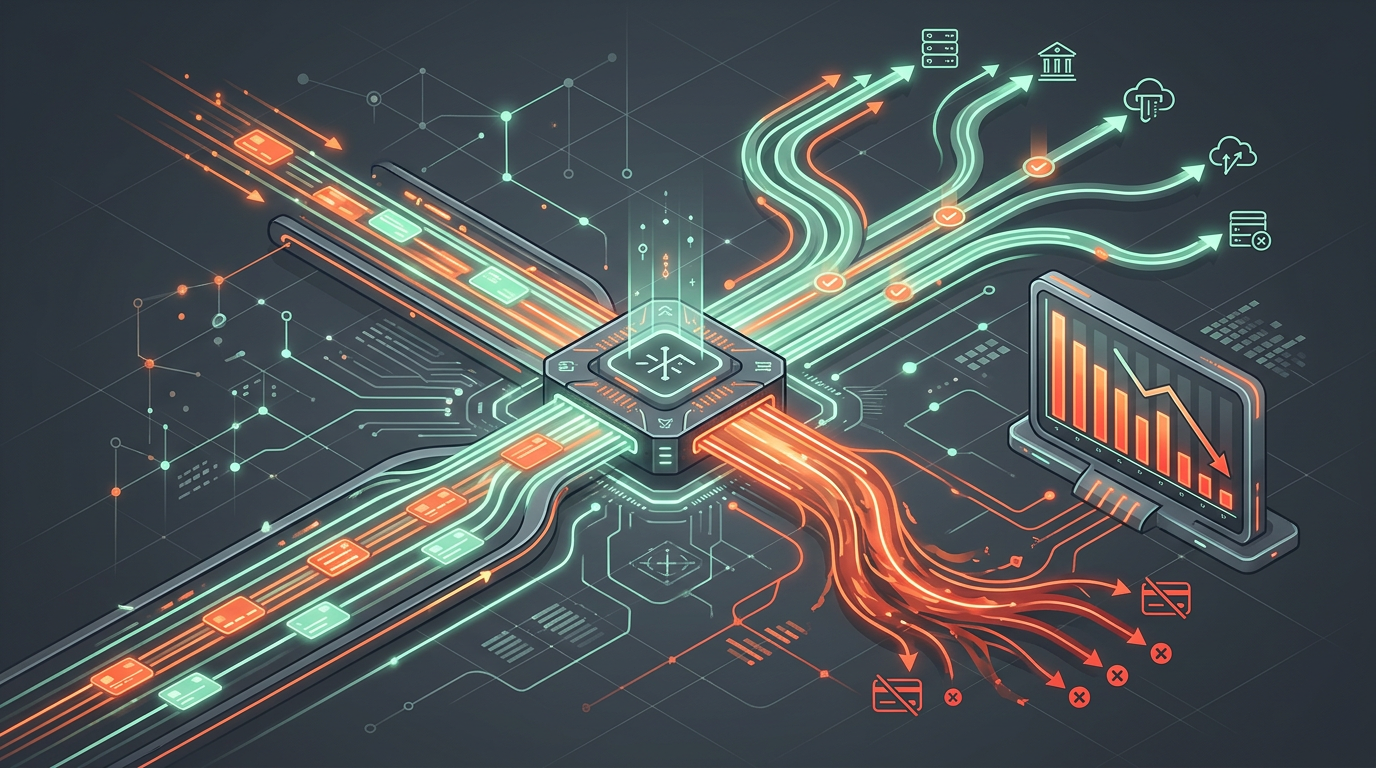
Mastercard announced October 11 the commercial rollout of Dynamic MCC Routing, a system that automatically directs gambling transactions to acquiring banks based on risk classification, reducing hard declines by an average of 8-12% in pilot deployments with 15 operators across North America and Europe.
The technology addresses a persistent pain point in gaming payments: legitimate transactions from recreational players are frequently declined due to overly strict MCC filtering rules or acquiring bank risk models, creating friction and abandonment in the checkout flow.
How It Works
Operators configure transaction risk tiers within Mastercard's merchant platform:
- Tier 1 (low-risk): Returning players with clean transaction history, verified identity, responsible gaming checks passed → routes to primary acquiring bank
- Tier 2 (medium-risk): New players with valid payment methods but limited history → routes to secondary acquirer with higher MCC tolerance
- Tier 3 (high-risk): Flagged accounts, velocity anomalies, or unverified identity → routes to tertiary acquirer or triggers manual review
The classification engine uses machine-learning models trained on operator data and Mastercard's fraud networks. Routing decisions execute in <50ms, imperceptible to the customer.
Early Results
In a 90-day pilot (July-September 2026) with 15 operators, average decline rates dropped from 7.2% to 6.0% for Tier 1-2 transactions. One North American sportsbook reported a 2% absolute decline in total payment failures, translating to approximately $1.2M in recovered monthly revenue.
Mastercard declined to identify specific pilot operators but confirmed participation from sportsbooks, online casinos, and poker operators in UK, Canada, and three EU jurisdictions.
Competitive Pressure
The rollout directly responds to Visa's restrictive MCC policies introduced in 2022, which many operators cite as a key cost driver. Visa has not announced comparable intelligent routing, though the company published a white paper in 2024 suggesting future evolution of its MCC framework.
Operators managing both Visa and Mastercard portfolios now have asymmetric incentives to shift transaction volume toward Mastercard, potentially reshaping acquiring relationships.
Compliance Architecture
Mastercard emphasized that dynamic routing does not bypass fraud or know-your-customer (KYC) checks. Operators must continue to run responsible gambling screens and AML verification; routing simply selects which acquirer processes the transaction.
The system logs all routing decisions for audit trails and regulatory reporting. Mastercard will provide quarterly analytics dashboards showing decline reasons, routing patterns, and fraud metrics by operator and geography.
Operational Considerations
Operators must integrate with Mastercard's merchant API to configure risk tiers and maintain updated player data. Integration typically takes 4-8 weeks. Support for Tier-3 manual review workflows is optional but recommended for operators managing accounts under regulatory scrutiny.
What's Next
Mastercard plans to add tokenization support by Q1 2027, allowing recurring transactions and subscriptions to benefit from dynamic routing without additional friction. American Express has indicated interest in developing comparable solutions, though no timeline has been announced.
The rollout signals that payment processors are increasingly willing to compete on gambling-specific features, a shift that suggests long-term stabilization of payment infrastructure after 3+ years of volatility in the category.
Source: Mastercard Merchant Services
Priya Sharma
Fintech Editor
Member of the iGaming Pulse editorial team. Covering industry news, analysis, and B2B developments across the global iGaming sector.